

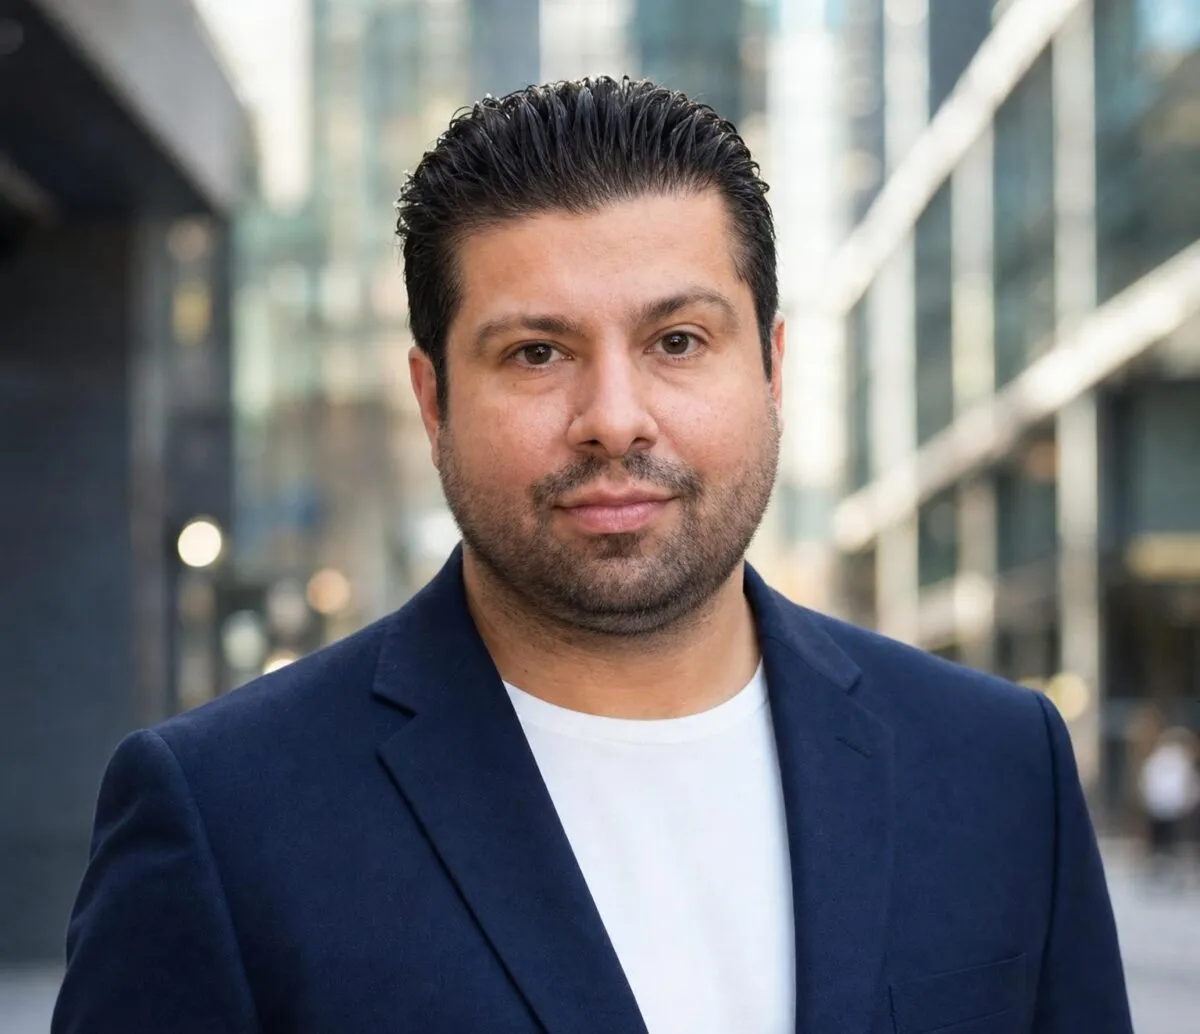
Photo courtesy: Neema Mahadavian
Most small business owners have never had a chief financial officer. They have a bookkeeper, a folder of receipts, an accountant they speak to in April, and a set of decisions they make alone. Hire now or wait a quarter. Take the loan at that rate. Raise prices before or after the busy season. Those decisions are the difference between a business that compounds and one that quietly stalls, and almost nobody making them has anyone to ask.
Neema Mahdavian has spent twenty years on the other side of that gap. He worked in fintech, banking and venture investing, built a financial services company and sold it to a major bank, and saw from inside how differently a bank treats a company with a finance department and a company without one. In May he launched QBiz Technology in Los Angeles as what he calls an AI business bank for entrepreneurs. Lending went live first, merchant payments followed in late July, and this month he has opened the piece he considers the actual product: an AI Business Advisor.
WHAT IT ACTUALLY DOES
The Advisor runs a guided session with an owner and hands back a plan of action, working from the accounts, lending activity and payment flows the owner already holds with QBiz. A free account includes five minutes with it. That sounds modest until you consider what an owner usually gets instead, which is a consultant they cannot afford or a general purpose chatbot that has never seen their cash flow.
The Mahdavian keeps returning to his location. Almost all of the AI now being sold to founders sits on top of a bank, connected to accounts through a data feed, able to advise but not to act. QBiz holds the deposits and makes the loans, so the advice and the money live in the same place. An owner who learns in a session that they will be short in six weeks is already inside the institution that can do something about it.
THE WEEK THE INDUSTRY MADE HIS POINT FOR HIM
The Advisor arrives in a crowded month, and the crowd is instructive. On September 10, cfo.ai, formerly Runway, launched Ari, an AI chief financial officer for founders that plugs into NetSuite, QuickBooks, Brex, Mercury and Stripe to keep a live financial model of a company. The same day, OpenAI released ChatGPT for Financial Services, built with Morgan Stanley and Evercore as design partners and starting where the money is oldest, in investment banking and equity research. Ripple expanded its governed AI for corporate treasury teams, and Paystand introduced what it calls digital employees for reporting, spend and collections.
Every one of those products is built for a finance function that already exists. A treasury team. An equity research desk. A founder with a data stack. The business owner with nine employees, an irregular cash cycle and no finance hire is not in that picture.
The numbers say she is trying anyway. The U.S. Chamber of Commerce found 89 per cent of American small businesses using AI in 2026, up from 36 per cent in 2023, one of the fastest adoption curves ever recorded in the sector. A Goldman Sachs 10,000 Small Businesses survey of 1,256 owners early this year found only 14 per cent had fully integrated it into how they operate. Adoption is nearly universal, integration is rare. What is missing is not enthusiasm, it is a tool that reaches the part of the business where money moves.
WHAT THE EARLY NUMBERS SHOW
QBiz says a business owner completes a loan application in two minutes and 47 seconds, in a category where the process is normally measured in days of paperwork. There are 156 loan applications in its pipeline and 102 merchant clients in roughly six weeks since payments launched. Seventy six per cent of users apply for at least one product, and 55 per cent apply for more than one.
That last figure is the one Mahdavian finds most telling. Owners arriving for a loan are not stopping at the loan. They are taking payments, accounts, whatever else is there, which suggests the gap is not a credit gap at all but a whole missing relationship.
THE LINE HE WILL NOT CROSS
For a company that is comfortable with AI, QBiz is notably unwilling to let it decide who gets a loan. That restraint is a choice rather than a limitation. In the same week the Advisor opened, the Mexican AI-driven institution Kapital raised 125 million dollars in equity and debt to build out its AI platform and expand in Mexico and the United States, and HyperVerge launched three AI underwriting agents for business lending, cutting financial assessments from hours to minutes. Even HyperVerge’s chief executive was clear that the final credit decision stays with a person.
Mahdavian’s position starts there rather than ending there. Live transaction data should inform a credit decision, and a human should own it. Every QBiz customer is assigned a relationship manager they can book time with, an expensive promise for a young bank and a deliberate one.
The full bank launches in January, which is the real test, because a bank that also advises has to be right about both. For now the claim is smaller and easier to check. The most capable financial AI built this year went to the institutions that serve the largest companies in the world. The owner who runs payroll herself got a chatbot. QBiz is betting she deserves what the big companies got, delivered by the institution that holds her money.
